The Radical Mindset Shift That Lets Ordinary People Retire Early—Even on a Teacher’s Salary
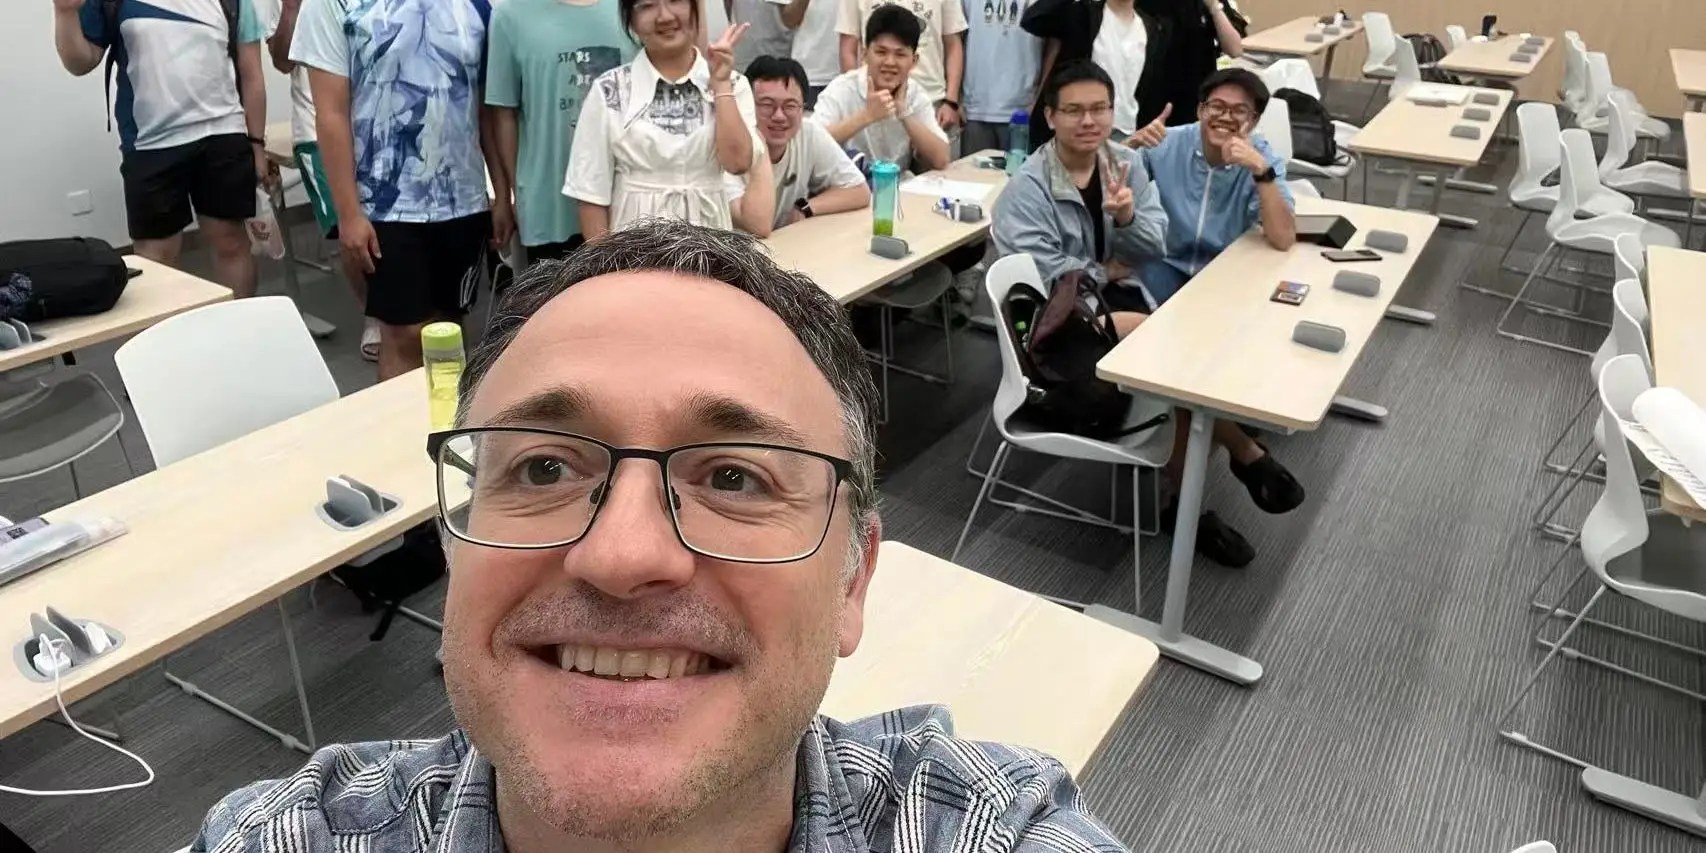
Let’s start with a provocative truth: Financial independence isn’t reserved for Silicon Valley executives or Wall Street titans. A 47-year-old professor in Shenzhen, China, has quietly dismantled the myth that you need a six-figure income to retire early. Miguel Marquez’s journey—from student debt to ‘Lean FI’ in less than a decade—reveals a blueprint that’s equal parts psychological hack, cultural rebellion, and financial engineering. What he’s built isn’t just a roadmap to quit your job; it’s a manifesto for redefining what ‘enough’ truly means.
Why the FIRE Movement Got One Crucial Thing Wrong
The FIRE (Financial Independence, Retire Early) community often feels like a cult obsessed with spreadsheet cells and withdrawal rates. But Marquez’s approach exposes a fatal flaw in mainstream FIRE philosophy: Its fixation on distant, monolithic goals paralyzes people. “I thought you needed a lot of money to solve the money problem,” he admits. That’s the crux. Most abandon their dreams of FI because the target feels like a mirage. His solution? Turn a marathon into a series of sprints.
Breaking FI into seven milestones—debt freedom, ‘F-you money,’ Coast FI, and so on—transforms abstract anxiety into actionable steps. This isn’t just clever math; it’s behavioral economics in practice. Each milestone delivers a dopamine hit, reinforcing the habit loop of saving and investing. The psychological genius? You get to feel like a winner before reaching the finish line.
F-You Money: The Most Underrated Form of Financial Power
Let’s dissect ‘F-you money,’ the second milestone. At its core, it’s one year’s expenses stashed away—enough to walk away from a soul-crushing job. But here’s what most miss: This isn’t about quitting impulsively. It’s about optionality. Marquez calls it “the cushion that creates options,” which sounds almost Zen when you realize what he’s really saying: Financial security isn’t about wealth accumulation; it’s about reclaiming agency.
I’d argue this stage matters more than any other because it flips the power dynamic overnight. Suddenly, you’re not trapped by mortgage payments or healthcare dependencies. You become the author of your time. And in an era of burnout culture and AI-driven job instability, that flexibility might be the ultimate hedge.
Coast FI: When Math Becomes Magic
Then there’s Coast FI—the point where your investments grow into full retirement savings without additional contributions. This is where compounding interest turns from abstract concept to personal genie. Marquez hit this milestone in under two years after moving to China, a detail that screams: Location is leverage.
What fascinates me here is the cultural contrast. An American professor might never reach Coast FI without a radical lifestyle shift. But in Shenzhen, where subsidized housing and low living costs exist, the math bends in your favor. It’s a reminder that FI isn’t just about saving 50% of your income; it’s about ruthlessly optimizing your environment.
Lean FI vs. Fat FI: Who Decides What ‘Enough’ Looks Like?
Now consider Lean FI, where investments cover essentials but leave little room for luxuries. Marquez happily lives here, funding “housing, food, fixed expenses, and an occasional short trip.” Meanwhile, Fat FI devotees chase portfolios large enough to sustain luxury lifestyles. But this dichotomy reveals something deeper: The FIRE spectrum mirrors society’s fractured relationship with consumption.
Here’s my hot take: Lean FI is the purest form of financial independence because it strips away ego. When Marquez says his $400k portfolio feels ‘abundant’ despite modest spending, he’s not just saving money—he’s rejecting the consumerist narrative that equates wealth with worth. Fat FI might buy bigger houses, but Lean FI buys freedom from societal expectations.
The Hidden Lesson: Geography as a Wealth Multiplier
Let’s address the elephant in the room: Marquez’s success hinges on living in China. His subsidized university housing and 30%-income-expense ratio would be unthinkable in most Western cities. This raises an uncomfortable question: Is the FIRE movement inherently biased toward high-cost countries? Or is the real secret sauce global mobility?
From my perspective, this aspect deserves more scrutiny. We fetishize remote work’s potential but rarely connect it to FI strategy. Marquez’s story suggests that geographic arbitrage isn’t just a tactic—it’s a paradigm shift. Moving abroad isn’t a cop-out; it’s recognizing that the rules of wealth-building vary dramatically by ZIP code.
Rethinking Abundance: The Psychological Frontier of FIRE
Ultimately, Marquez’s journey forces us to confront what financial independence really means. Is it about escaping work? Or about crafting a life where every hour aligns with your values? His answer is clear: He doesn’t care about Fat FI because his definition of abundance has shifted. This echoes Stoic philosophy—mastery over desires, not possessions, is true wealth.
What does this mean for the rest of us? The seven milestones aren’t just financial targets; they’re a cognitive retraining program. Each level forces introspection: How much do you really need? What trade-offs are you making? Why does ‘retirement’ still feel decades away when the math says otherwise?
The Future of FIRE: Smaller Goals, Bigger Lives
Here’s the revolutionary takeaway: FI isn’t a single finish line; it’s a Choose Your Own Adventure game. By fracturing the journey into milestones, Marquez didn’t just make retirement planning accessible—he made it human. This approach could democratize financial independence in a world where 56% of Americans couldn’t cover a $1,000 emergency expense.
Will this framework work for everyone? Of course not. But it challenges us to think differently about debt, savings, and lifestyle design. If there’s one truth I’ve gleaned from analyzing Marquez’s story, it’s this: The path to freedom isn’t paved with higher salaries—it’s built by redefining what counts as ‘winning’ in the first place.